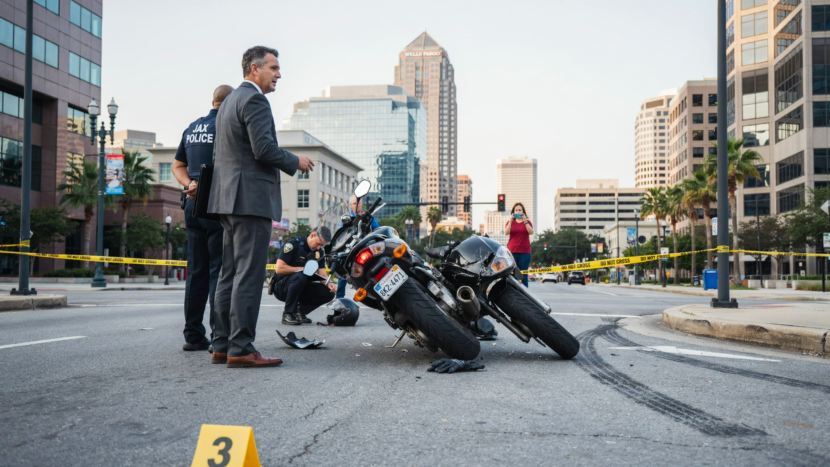
Insurance companies may undervalue Florida motorcycle accident claims by disputing fault, relying on stereotypes about riders, or questioning whether injuries resulted from the crash. Early offers may also overlook future treatment, lost earning capacity, and non-economic harm, particularly when medical records are incomplete.
Florida’s modified comparative negligence law can reduce compensation based on a rider’s share of fault and generally bars recovery if that share exceeds 50%. The Law Offices of Anidjar and Levine can help explain how evidence, coverage, and deadlines may affect an offer. Learn more from a Jacksonville Motorcycle Accident Lawyer.
Why Are Florida Motorcycle Settlement Offers Low?
Florida motorcycle settlement offers are often low because insurers assess claims through a financial lens, not the rider’s full experience. Early offers may reflect uncertainty about liability, incomplete medical records, or a desire to resolve a claim before its long-term effects are clear. For injured riders, accepting too soon can leave future treatment, lost income, or lasting limitations uncompensated.
Florida’s comparative negligence rules can also affect negotiations. If an insurer argues that a rider shares responsibility, it may seek to reduce the amount paid. Available coverage also matters: Policy limits may cap recovery, even when documented losses exceed the insured amount. Additional coverage or responsible parties may warrant review.
Insurer incentives include controlling claim costs and limiting exposure, which can shape initial proposals. A careful response should consider the crash evidence, applicable Florida law, and the rider’s documented needs. Attorneys serving injured people can help evaluate an offer, identify coverage questions, and explain options without promising a particular outcome.
How Do Insurers Value Motorcycle Accident Claims?
How do insurers value motorcycle accident claims? In Florida, adjusters generally assess documented economic losses, including medical expenses, future treatment, lost income, and reduced earning capacity. They also evaluate non-economic harm, such as pain, disability, disfigurement, and loss of enjoyment of life. The strength of medical records, treatment consistency, and credible evidence of lasting effects can influence the valuation.
Insurers compare claimed damages with available policy limits, which may limit recovery even when losses are substantial. Florida’s personal injury protection system typically does not cover motorcycles, so injured riders may need to pursue compensation through applicable liability coverage or other available policies. The specific coverage and policy terms matter.
Settlement negotiation tactics may include challenging bills, questioning future care estimates, or presenting an early offer before the full medical picture is known. Carefully reviewing records, expenses, and coverage helps you build a supported demand. Riders serving their families and communities benefit from understanding how documented losses shape negotiations and when professional legal guidance may help evaluate an offer.
How Can Fault Disputes Lower Your Offer?
In Florida, an insurer may reduce a motorcycle accident offer if it assigns the rider a share of fault, reducing compensation under the state’s comparative-fault rules. Conflicting accounts can create doubt about who caused the crash and how responsibility should be divided. Disputed evidence may also delay settlement while the parties investigate liability.
Shared Fault Reduces Compensation
When an insurer argues that a motorcyclist shares blame for a crash, Florida’s comparative-fault rules can reduce the compensation offered. Under Florida’s modified comparative negligence system, an injured rider generally cannot recover damages if found more than 50% responsible. At 50% or less, compensation is reduced by the rider’s assigned share of fault. This shared liability can affect payment for medical care, lost income, and other losses.
An insurer may point to details such as:
- A motorcycle’s position near a lane line
- A rider’s speed before impact
- A missed signal at an intersection
- A helmet’s condition after the collision
- A delayed response to a hazard
Each allegation can shift the fault percentage and lower an offer. Careful review of Florida traffic rules, crash evidence, and documented losses helps assess whether that allocation is fair and supports a more accurate claim valuation.
Conflicting Accounts Create Doubt
Conflicting accounts can make a Florida motorcycle claim harder to value because insurers may question who caused the crash or how it happened. When the rider and driver describe different movements, signals, or points of impact, an adjuster may treat fault as uncertain and make a lower offer. Witness credibility can influence that assessment, particularly when witnesses disagree or had limited views of the collision. Timeline inconsistencies—such as differing accounts of when a turn began or when the motorcycle entered an intersection—may also weaken confidence in either version. Under Florida’s comparative negligence rules, a disputed account can lead an insurer to assign the rider a greater share of responsibility, reducing potential recovery. Clear, consistent statements help present the rider’s experience accurately and support a fair evaluation of the claim.
Disputed Evidence Delays Settlement
Disputed evidence can delay a Florida motorcycle claim and give an insurer grounds to reduce its offer. When drivers disagree about a crash, adjusters may question who caused it, how injuries occurred, or whether damages are related. Under Florida’s comparative-fault rules, an insurer may assign the rider a share of responsibility and lower the proposed payment accordingly. Careful review can help clarify what happened and support a fair resolution.
- A faded skid mark may leave braking distance uncertain.
- A damaged helmet can show impact, but not alone establish fault.
- A missing traffic-camera recording may erase a crucial moment.
- Witness availability can decline as memories fade or people move.
- Delayed Evidence preservation may allow vehicle damage or roadway conditions to change.
Prompt documentation, medical records, photographs, and independent witness statements can help address disputes. A Florida attorney can assess evidence and challenge unsupported fault allocations.
Can Bias Against Riders Affect Your Claim?
Bias against motorcyclists can affect how an insurer evaluates a Florida accident claim, even when the evidence shows another driver caused the crash. Rider stereotypes may lead adjusters to view a motorcyclist as reckless or responsible without fairly weighing the facts. These unfair assumptions can influence fault assessments, settlement discussions, and the credibility assigned to each account.
Florida follows a modified comparative negligence system. A claimant may recover damages if found no more than 50 percent at fault, but compensation is reduced by the claimant’s share of responsibility. An insurer’s biased evaluation of fault can consequently have significant financial consequences.
To counter unsupported assumptions, a claim should be grounded in objective evidence, such as the crash report, witness statements, photographs, and applicable traffic laws. A clear record can help show how the collision occurred and who had the legal duty to prevent it. Fair evaluation matters not only to the injured rider, but also to families and communities affected by preventable crashes.
How Do Insurers Challenge Injury Severity?
Florida insurers may scrutinize medical records, imaging, and treatment history to dispute the severity or cause of a motorcyclist’s injuries. They may also argue that symptoms are minor, preexisting, or have little effect on daily activities and work. Clear, consistent medical documentation can help address these challenges when evaluating a claim.
Questioning Medical Evidence
How do insurers assess the severity of a motorcycle rider’s injuries? In Florida claims, adjusters may scrutinize medical records, diagnostic imaging, and treatment chronology to test whether documented conditions support the reported harm. Their review may focus on:
- X-rays showing fractures or alignment changes
- MRI findings documenting soft-tissue or spinal injuries
- Emergency-room notes recorded soon after the crash
- Follow-up visits tracing symptoms and clinical findings
- Consultant referrals, prescriptions, and recommended procedures
Insurers may question gaps in care, differing provider opinions, or whether a scan clearly connects an injury to the collision. These challenges can affect claim valuation, even when a rider has followed medical advice. Consistent records help clarify the injury’s course and support fair consideration of necessary care. Florida riders can preserve visit summaries and imaging reports for counsel’s review, helping present a coherent account of treatment and recovery needs.
Minimizing Injury Impact
Even when medical records document an injury, insurers may argue that its effects are less serious or shorter-lived than claimed. They may point to gaps in treatment, prior conditions, or routine activities as evidence that a rider has recovered. Yet intermittent care can reflect cost, access, or medical advice—not an absence of pain. Pain management records, expert recommendations, and testimony from treating providers can help explain ongoing limitations and the need for future care.
Insurers may also discount emotional distress, including anxiety about riding, sleep disruption, or reduced independence. Florida claimants can support these effects with consistent treatment records and clear accounts of daily changes. A careful damages presentation connects the crash to documented physical and emotional consequences without overstating them. This evidence helps insurers assess the full impact on the injured person and those who depend on them.
What Damages Should a Settlement Cover?
A fair motorcycle accident settlement in Florida should account for both financial losses and the personal harm caused by the crash. The value depends on evidence, injury severity, and how the collision affected the rider’s daily life. Florida law may allow recovery of documented economic losses and non-economic damages when another party is legally responsible.
A claim may include:
- Emergency-room charges and other medical bills already incurred
- Lost wages shown by pay records or employer statements
- Reduced earning capacity when injuries limit work
- Property damage, including motorcycle repairs or its fair market value
- Pain, suffering, and emotional distress supported by treatment records and testimony
Receipts, photographs, witness accounts, and medical documentation can help show the full impact, rather than leaving an insurer to rely on a narrow estimate. Florida’s comparative-fault rules may reduce compensation if the rider shares responsibility, and applicable deadlines can affect the right to recover. A carefully supported demand helps confirm that the settlement reflects losses and recognizes the rider’s family and community responsibilities.
Are Future Medical Costs Included?
Future medical costs may be included in a Florida motorcycle accident claim when the evidence supports the need for continued care. This can cover projected treatment expenses, such as surgery, rehabilitation, and medication. Claims may also account for long-term care needs arising from permanent injuries.
Projected Treatment Expenses
When a Florida motorcycle crash causes lasting injuries, the value of a claim may depend on medical care the rider will need after settlement. Projected treatment expenses can include care supported by medical records, provider opinions, and a reasonable prognosis. Florida claims should distinguish documented future needs from speculation; insurers may challenge estimates that lack clinical support.
- Follow-up imaging to monitor a fracture’s recovery
- A surgeon’s recommended procedure and facility charges
- Rehabilitation cost projections for restoring mobility
- Consultant consultation fees for evaluating nerve damage
- Prescription costs tied to the diagnosed injury
A treating provider’s plan can help show why each expense is medically necessary and reasonably likely. Itemized estimates and expert opinions may strengthen a demand, while unsupported figures can invite disputes. Including credible projections helps account for treatment without shifting avoidable costs onto injured riders or their families. Future expenses should be evaluated separately from care already received, with estimates grounded in the individual’s injuries and recovery outlook.
Long-Term Care Needs
If a Florida motorcycle crash leaves a rider with lasting impairments, a claim may include the reasonable cost of long-term care supported by medical evidence. Future damages can cover needs extending beyond immediate treatment, but insurers may challenge their duration, necessity, or projected price. A life-care plan, treating-provider opinions, and reliable cost estimates can help document the claim.
| Care need | Supporting evidence | Potential expense |
|---|---|---|
| In-home assistance | Functional assessment | Caregiver support |
| Home modifications | Occupational therapy evaluation | Ramps, accessible fixtures |
| Ongoing therapy | Treatment records | Rehabilitation sessions |
Florida claims must connect anticipated costs to crash-related injuries, not speculation. Documentation should explain how care supports safety, dignity, and daily independence. When a serious injury requires lifelong assistance, an incomplete valuation may omit substantial future medical costs. Careful review can help make certain the injured rider’s needs are presented fully and fairly.
How Does Lost Income Affect Your Claim?
Lost income can increase the value of a Florida motorcycle accident claim, but insurers may dispute whether the missed work and claimed amount are supported by evidence. Recoverable damages may include wages lost during recovery and, when injuries limit future employment, reduced earning capacity. A claim should reflect the actual financial effect, not an inflated estimate.
Lost wages and reduced earning capacity may increase a Florida motorcycle accident claim when supported by evidence.
- A missed shift leaves a gap in a weekly paycheck.
- Missed overtime removes income earned beyond regular hours.
- A temporary work restriction keeps an employee from full duties.
- A lasting injury may narrow future job opportunities.
- Self-employment interruptions can delay customer work and revenue.
Florida claims may account for these losses when they are causally connected to the crash and reasonably established. The impact can extend beyond one injured worker: reduced household income may affect dependents, caregiving, and the ability to meet ordinary obligations. Insurers may scrutinize whether time away was necessary and whether claimed future losses are reasonably likely. Accurate calculations help present the full economic impact without overstating it.
What Evidence Supports a Fair Offer?
A fair motorcycle accident offer in Florida should account for medical records and bills documenting the injuries and treatment. Photographs, witness statements, and other accident-scene evidence can help establish how the crash occurred and who was at fault. Pay records and reliable projections of future expenses can also support claims for lost wages and ongoing costs.
Medical Records and Bills
Because an insurer’s initial offer often reflects only the records it has received, Florida motorcycle accident claims should be supported by complete medical records and itemized bills linking treatment to the crash. A clear treatment chronology can show how injuries progressed, why care was needed, and whether providers’ recommendations were followed. Useful documentation includes:
- Emergency department notes describing initial symptoms and findings.
- Imaging reports identifying fractures or other injuries.
- Expert evaluations and prescribed treatment plans.
- Physical therapy notes tracking pain, mobility, and progress.
- Itemized medical bills showing charges, payments, and balances.
These records help an adjuster assess past expenses and understand ongoing care needs. Florida claimants should request records from every treating provider and check for missing dates, duplicate charges, or inaccurate entries. Consistent documentation can support a fair evaluation while helping guarantee that the claim reflects the injured person’s actual medical burden.
Accident Scene Evidence
Medical records document an injured rider’s losses, while accident-scene evidence can help establish how the crash occurred and who may be responsible. In Florida, photographs, video, and witness statements may preserve details that disappear after vehicles are moved or roadways cleared. Skid mark analysis can help assess braking, speed, and vehicle movement, while debris field mapping may indicate points of impact and the direction of travel. Investigators may also document sight lines, traffic controls, road conditions, and damage to the motorcycle and other vehicles. These details can test an insurer’s account of fault and support a fair evaluation under Florida’s comparative negligence rules. Prompt, careful evidence collection can protect the rider’s ability to present a clear claim and help decision-makers assess responsibility based on the available facts.
Lost Wages and Future Costs
Lost wages and future costs should be supported by records that connect the motorcycle crash to specific financial losses. In Florida, insurers may question missed work or projected expenses unless medical evidence and employment records establish their cause and likely duration. A well-documented claim can show how injuries affect both household stability and the injured person’s ability to serve family, coworkers, and community.
- Pay stubs, tax returns, and employer statements showing missed shifts and lost income.
- Physician restrictions linking crash injuries to time away from work.
- Medical opinions estimating future treatment, medication, or assistive-device costs.
- Vocational rehabilitation assessments identifying retraining needs and realistic job options.
- Expert analysis of Reduced earning capacity, including diminished future earnings.
When injuries prevent a return to the same occupation, credible projections should explain assumptions and account for available work. Organized, consistent evidence helps an insurer evaluate a fair offer rather than discounting future losses as speculative.
How Do You Compare an Offer to Your Losses?
Before deciding whether an insurer’s offer is fair, a Florida motorcyclist should compare it with the full value of the losses caused by the crash—not just current bills. Loss documentation helps establish that value. Records may include medical invoices, treatment notes, prescription costs, repair estimates, pay records, and proof of missed work. A complete accounting should also consider reasonably anticipated care, reduced earning capacity, and the effect of lasting injuries on daily activities.
In Florida, the available recovery may depend on fault, insurance coverage, and applicable legal limits. A rider’s own negligence can reduce damages under the state’s comparative-fault rules, while policy terms may constrain payment. The offer comparison should accordingly match each documented loss to the amount proposed, identify categories omitted or discounted, and account for non-economic harm such as pain and loss of normal function. Organized evidence allows the rider and any representative to assess whether the proposed amount reflects the claim’s supported value, rather than only the insurer’s initial estimate.
Should You Accept the First Settlement Offer?
A Florida motorcyclist generally should not accept the first settlement offer until the full extent of the injuries, financial losses, and available insurance coverage is reasonably clear. Early payments may arrive before doctors can assess lasting impairment or future treatment needs. A signed release can also end claims against responsible parties, even when later expenses emerge.
Before deciding, the rider may consider:
- Whether fractures, road rash, or head injuries have fully recovered.
- Whether follow-up care, rehabilitation, or medication remains necessary.
- Whether missed work or reduced earning capacity is documented.
- Whether available liability policies and applicable coverage are identified.
- Whether Release Terms waive future claims or include other parties.
Negotiation Timing matters: Florida’s filing deadlines and policy limits can affect a claim, but urgency alone does not make an offer fair. A careful review helps preserve resources for recovery and family responsibilities. Because settlement decisions are usually final, a Florida attorney can review the offer, medical outlook, and release language before you accept.
How Can You Respond to a Low Offer?
When a Florida motorcycle insurer’s first offer falls short, the injured rider can respond with a documented counteroffer instead of accepting or rejecting it without explanation. A focused response should identify what the offer overlooks and support the requested amount with evidence.
Useful records may include medical bills, treatment plans, wage-loss documentation, repair estimates, photographs, and proof of how injuries affect daily responsibilities. Florida’s comparative-fault rules can also influence valuation, so the rider should address any disputed account of the crash with relevant evidence, such as the police report or witness statements.
A sound Counteroffer strategy links each claimed loss to documentation and explains anticipated future care, supported by medical providers. During settlement negotiation, clear, professional communication can help keep discussions grounded in the claim’s facts rather than pressure or assumptions. The rider should review proposed release terms carefully and consider legal guidance before signing, because a settlement may affect the ability to pursue compensation for injuries and losses.
What Happens If You Reject the Offer?
Rejecting a settlement offer does not end a Florida motorcycle accident claim; it leaves the claim unresolved while negotiations may continue. The insurer may request additional records, reassess liability, or stand firm. The injured rider can respond with evidence of medical costs, lost income, property damage, and the crash’s effects on daily life.
Rejecting an offer keeps a Florida motorcycle claim unresolved, allowing negotiations and evidence review to continue.
A rejection may lead to:
- A revised offer arriving after updated treatment records.
- A request for repair estimates or photographs of the damaged motorcycle.
- A discussion of Florida’s comparative-fault rules and each party’s responsibility.
- A Negotiation deadline set by the insurer, which you should review carefully.
- Continued disagreement that may require legal guidance about available options.
Rejecting an offer alone generally does not cause Claim withdrawal, but settlement documents, insurer communications, or policy terms may affect the claim. A rider should avoid signing a release without understanding its effect; accepting a settlement commonly ends claims covered by that release. Careful documentation can help protect the injured person’s interests during negotiations.
How Long Do You Have to File in Florida?
In Florida, an injured motorcyclist generally has two years from the crash date to file a negligence lawsuit, though exceptions may change the deadline. This filing deadline comes from Florida’s statute of limitations for negligence claims. Missing it can prevent recovery through court, regardless of the claim’s substance or the insurer’s earlier settlement discussions.
The deadline may differ in limited circumstances. For example, claims involving a government entity can require formal notice and shorter time limits. A claim for injuries discovered later may raise questions about when the limitations period began, but Florida’s discovery rule does not generally extend the deadline for ordinary crash injuries. Wrongful death claims also have a separate limitations period, typically measured from the date of death.
Because deadlines depend on the claim, parties, and facts, the applicable date should be verified rather than assumed. Preserving records and documenting losses can support an accurate assessment of damages, but neither action pauses the statutory clock. A timely filing protects the injured person’s opportunity to seek fair compensation and serve family responsibilities.
When Should You Talk to a Florida Motorcycle Accident Lawyer?
A Florida motorcycle accident lawyer can help evaluate a claim before insurer negotiations or filing deadlines limit the rider’s options. Early advice may preserve evidence, clarify available coverage, and prevent a quick settlement from overlooking future treatment or lost income. Florida’s comparative-fault rules can also affect recovery, making a careful review of crash facts important.
An Initial consultation gives the rider an opportunity to discuss the collision, medical care, and insurer communications. Useful details include:
- A damaged helmet beside the motorcycle
- Photos of the intersection and skid marks
- Names and contact information for witnesses
- Medical records, bills, and work-loss notes
- The insurer’s letters and settlement offers
Prompt attorney selection matters when injuries are serious, fault is disputed, or an adjuster requests a recorded statement or release. A lawyer can explain deadlines, including the applicable statute of limitations, and identify next steps without promising a particular result. Riders who serve family, coworkers, or community members may benefit from guidance that protects their health and claim while they focus on recuperation.
Frequently Asked Questions
Does Florida Require Motorcycle Riders to Carry Personal Injury Protection Insurance?
Florida generally does not require motorcycle riders to carry personal injury protection; the Florida motorcycle PIP exemption applies because motorcycles are excluded from mandatory PIP coverage. Riders may consider motorcycle medical coverage options, including health insurance or motorcycle medical-payments coverage.
Can Passengers File Claims After a Florida Motorcycle Accident?
Yes. Passengers injured in Florida motorcycle crashes may pursue Passenger injury claims against responsible drivers, including the operator. Shared liability can affect recovery, and Florida’s comparative negligence rules may reduce compensation when a passenger contributed to the crash.
How Does Helmet Use Affect a Florida Motorcycle Accident Claim?
Helmet use may affect a Florida motorcycle accident claim by influencing injury severity and damages, but not automatically determining fault. Florida’s helmet law generally permits riders aged 21 or older with qualifying insurance coverage to ride helmet-free.
Can I Recover Compensation if I Wasn’t Wearing a Helmet?
Yes, an injured rider may recover compensation in Florida even if they weren’t wearing a helmet. The helmet law and comparative negligence may affect fault or damages, but insurers cannot automatically deny an otherwise valid claim solely for helmet nonuse.
What Happens if the At-Fault Driver Has No Insurance?
If the at-fault driver lacks insurance, an injured motorcyclist may seek compensation through Uninsured motorist coverage, if purchased, or pursue the driver’s Personal assets. Florida-specific coverage terms and collectability affect available recovery options.
Florida motorcycle accident claims may be undervalued when insurers dispute fault, question injuries, or rely on assumptions about riders. A careful review of medical records, crash evidence, and settlement calculations can help identify gaps in an offer. Injured riders should understand the scope of a settlement and track Florida’s filing deadline before accepting an offer. When negotiations stall or liability is contested, the Jacksonville Motorcycle Accident Lawyer at Law Offices of Anidjar and Levine can explain available options and help protect the claim.